BuddhistCatholicContemplativeEvangelicalGeneral ChristianHinduJewishLatter-day SaintMuslimNew VisionsProgressive Christian
Beliefs
- Buddhist
- Catholic
- Contemplative
- Evangelical
- General Christian
- Hindu
- Jewish
- Latter-day Saint
- More Voices
- Muslim
- New Visions
- Pagan
- Progressive Christian
Topics
- Religion News
- Food and Religion
- Sports and Religion
- Religious Art
- Religious Music and Entertainment
- Religious Events
- History and Religion
- Style and Religion
- Politics and Religion
- Women in Religion
- Recreation Outdoors and Religion
- Business Finance and Religion
- Careers Workplace and Religion
- Education and Religion
- Family Parenting and Religion
- Health Fitness and Religion
- Home and Religion
- Relationships and Religion
- Technology and Religion
- Travel and Religion
Columnists
- Buddhist Columnists
- Business Finance and Religion Columnists
- Careers Workplace and Religion Columnists
- Catholic Columnists
- Contemplative Columnists
- Education and Religion Columnists
- Evangelists Columnists
- Family Parenting and Religion Columnists
- General Christian Columnists
- Health Fitness and Religion Columnists
- Hindu Columnists
- History and Religion Columnists
- Home and Religion Columnists
- Jewish Columnists
- More Voices Columnists
- Latter Day Columnists
- Muslim Columnists
- New Visions Columnists
- Nonreligious Columnists
- Pagan Columnists
- Politics and Religion Columnists
- Progressive Columnists
- Recreation Outdoors and Religion Columnists
- Relationships and Religion Columnists
- Religion News Columnists
- Religious Art Columnists
- Religious Events Columnists
- Religious Music and Entertainment Columnists
- Sports and Religion Columnists
- Style and Religion Columnists
- Technology and Religion Columnists
- Travel and Religion Columnists
- Women in Religion Columnists
Resource Library
- 2026 Calendar
- Library of World Religions
- The 100 Most Holy Places on Earth
- Patheos Answers
- Podcasts
- Videos
- Faith Leaders Database
- Anglican Episcopalian
- Bahai
- Baptist
- Buddhism
- Christianity
- Confucianism
- Eastern Orthodoxy
- Hinduism
- Holiness and Pentecostal
- ISKCON
- Islam
- Judaism
- Lutheran
- Methodist
- The Church of Jesus Christ of Latter-day Saints
- New Age
- Paganism
- Presbytarian and Reformed
- Protestantism
- Religion Behind the Scenes
- Roman Catholic
- Scientology
- Shia Islam
- Sikhism
- Sufism
- Sunni Islam
- Taoism
- Zen
- See all religions
Research Tools
 Ad-Free & Subscriber Log-In Subscription Support
Follow Patheos 

- Trending:
- Forgiveness
- |
- Marriage
- |
- Consciousness
- |
- Death Penalty
- |
- Election
- |
- Halloween
 Faith With Wisdom
- Home
- Progressive Christian
- Modern Usury & the Failure of Christian Ethics
Modern Usury & the Failure of Christian Ethics
Last updated on: June 9, 2011 at 3:09 pm by Paul Jesep
Modern Usury & the Failure of Christian Ethics 2011-06-09T15:09:53-06:00 Paul Jesep
Patheos Explore the world's faith through different perspectives on religion and spirituality! Patheos has the views of the prevalent religions and spiritualities of the world.
Over 2,000 years ago Jesus shared values, teachings, and a way of life when there
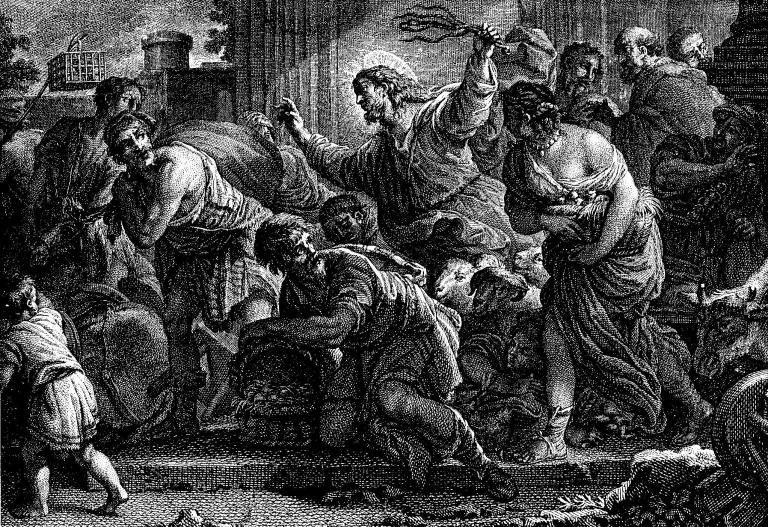
Jesus Chases Out the Money Changers
were no credit cards and collection agencies. Nor were there arbitrary credit or Fair, Isaac and Company (FICO) scores which are now used to determine eligibility for employment, car loans, home ownership, student loans, and apartment rentals. The interconnected industries of banks, credit bureaus, and collection agencies have an enormous impact on the spiritual, emotional, and physical well-being of families and individuals.
According to one psychologist, up to 16 million Americans suffer from physical or emotional stress from consumer debt. It can lead to divorce, suicide, insomnia, anxiety, chronic headaches, stomach disorders, alcohol abuse and contribute to heart disease. This problem is found throughout the world.
People tend to feel shame that they’re in debt. In the United States, citizens have been conditioned to believe that if they haven’t succeeded at living the American dream, it’s their fault.
Surveys show that one out of three families in the United States use credit cards to help cover basic living expenses. The perception that those in debt have been living the good life is incorrect. Illness, unemployment, and meeting daily needs place most in debt.
It is legal in America to charge 79.9 percent interest on a credit card. Usury laws no longer exist. Some argue that it is a person’s choice to have credit cards with interest at 18 percent, 21 percent, 29 percent or higher. There is a strong belief among many Christians that indebtedness is the fault of the individual. Christian Darwinian-capitalist logic holds sway among many.
Independent of people not fully understanding the impact of high credit card interest rates on the household budget, however, there is the broader issue that plastic is the primary way to establish a credit score. Absent a credit history, functioning in modern society becomes difficult. This rigged system inevitably leads many to live with crushing debt.
A poor credit score can deny someone employment, a mortgage, rental housing and student loans. Or it can result in a higher cost for such necessities as car insurance. These scores are based on an imprecise formula. The person assigned the score has no recourse to challenge it. Credit bureaus have extraordinary power over the daily lives of people. It is a yet-to-be recognized human rights problem.
In 2007, 35 percent of employers used credit scores to assess a candidate’s qualifications, according to Ben Arnoldy, a Christian Science Monitor reporter who has written about credit checks as a civil rights issue. Another journalist, John Schoen of MSNBC, recently wrote about a survey of 100 employers by the Society of Human Resource Management that found 60 percent of respondents used credit histories to determine employment suitability.
Consumer advocates have consistently argued that there is no connection between consumer debt and job performance. It’s likely that Wall Street titans all had sterling credit scores, yet it didn’t stop them from unethical behavior that caused a historic financial crisis that necessitated taxpayer bailouts.
In addition, collection agencies are an industry that profits from financially wounded and vulnerable families and individuals. Studies have found that agencies often try to collect on debt never owed or past the statute of limitations. Tactics are often abusive. Frequently, judgments are given without documentation by the creditor. Even worse, many alleged debtors never receive notice that they are being sued. In some cases, creditors are using the courts to arrest alleged debtors for their failure to appear in court.
In light of the size of consumer debt and the interest rates being paid on it – does this reflect an economy that “works for people” or one that requires them to work for it? In working for the economy who is the beneficiary?
In Britain it’s been reported that some taxpayer bailout money was used for bank bonuses. In the United States, bank profits and bonuses are up. In 2010, President Obama called bank bonues “obscene.” Late last year bank profits were described as “pre-crisis heights.” In the first quarter of 2011, bank income, according to the Journal of Accountancy, “grew 66.5% from $17.4 billion in the year-ago period to the highest level since the second quarter of 2007—before the financial crisis.”
How does a family or individual get out of ever increasing debt caused by the existing financial structure? When financial burden becomes destructive does a group merit mercy, another justice, or perhaps neither since free choice has played a role? Has complacency by Christians replaced the social activism of Jesus?
Honest reflection is needed as to whether Christians have permitted, condoned, or legitimized inherent flaws in the existing economic framework. Have Christians failed to be their brother and sister’s keeper in this area of the economy? Can an active love of God be complacent in the face of this form of economic injustice?
Christian ethical models are needed to evaluate the policies and repercussions of loaning and the charging of interest. The meaning of corporate responsibility and good corporate citizenship must be discussed. Christians who work in the financial services industries need to be challenged with concerns about the rates and policies that they set and justify. Are they being good Christians? Have they lost their way and are their spiritual leaders showing them a better way?
Although the focus in this commentary is on the practices of collection agencies, credit bureaus, and credit card companies, Christian ethicists should include at some point mortgages, car loans, and student loan debt. Education debt now exceeds $829 billion which, for the first time in history, is higher than revolving credit which stands at $826.5 billion owed. Students are earning degrees in fields which will not correspond to the salaries needed to pay off the debt.
Throughout human history there have been laws and social condemnation of usurious practices by most religions. Aristotle called usury “the breeding of money.” He added that “usury is money bred of money . . . of all forms of money-making it is most against nature.” In the Hebrew Scriptures “usury” is the charging of any interest. Martin Luther observed that “Greed and usury have burst in like a great flood and have attained a semblance of legality.” In the Nineteenth Century Henry Campbell Black defined usury as “an illegal rate of interest . . . A usurious loan is one whose interest rates are determined to be in excess of those permitted by the usury laws.” It can, however, also be an “unconscionable and exorbitant rate or amount of interest.” Thus it’s legal, but unconscionable. In Dante’s Inferno usurers were placed below murderers in the seventh circle.
Regulations or prohibitions against usury existed at the time of Hammurabi’s Code in 1750 B.C. Rome’s Twelve Tables capped interest rates at 8 1/3% in 443 B.C. and the Code of Justinian at 8 1/3% in 529 A.D. Charlemagne outlawed usury in 800 A.D. Medieval Canon Law made usury punishable with ex-communication. Elizabeth I of England capped the charging of interest to no more than 10%. In 18th Century America the rate was capped at 8%. After the American Revolution most states kept interest rates at 6%.
In the early Twentieth Century usury laws were drastically scaled back in the United States. In 1978, the U.S. Supreme Court permitted South Dakota, home to a thriving credit card industry, to impose high consumer loan rates to those outside the state.
According to a money advice coordinator in the United Kingdom, if credit card rates were capped and reduced short-term consumer debt could drop by as much as fifty percent.[2] In July 2010, Elizabeth Warren, Harvard professor and originator of the Bureau of Consumer Financial Protection said that “Meaningful rules in the consumer credit market can accelerate economic recovery” in the United States.[3] Consumer debt is a factor in the decline of America’s middle class.[4] It contributes to economic inequality.[5]
Warren further told an interviewer that by better keeping banks in check consumers will be less exploited and have more money in their pockets. This economic freedom along with other legal oversight will free and empower average Americans to weed “out all the tricks and traps that sap families of billions of dollars annually.”[6] It’s worth emphasizing “more money in their pockets.” This money could help to grow the economy out of the recession.
Religious leaders have fought to end slavery, segregation and denying women the right to vote. They have championed labor laws, affordable housing and national health insurance. Yet most voices of faith are silent against the unjust gain of the credit card industry and the extraordinary harm being caused by credit bureaus and collection agencies. It is a worldwide problem. Perhaps it merits United Nations involvement.
Consumer debt should be paid back at a fair interest rate. At the same time, though, no one should become a permanent revenue source through unjust gain. Christian ethics has failed in one of the most overlooked, if not ignored, civil and human rights issue in the world today. Although there are other forms of economic injustice needing to be acknowledged and addressed, this one is particularly onerous on the poor and working middle class. The exploitation should be included in any definition of social injustice. Religious leaders should consider preaching against usury and calling on the faithful to press their elected officials to take action.
Paul is author of Credit Card Usury and the Christian Failure to Stop It — A Call to Social Justice Against the Money Changers.
© Paul Peter Jesep 2011
[1] See Chuck Collins and Mary Wright, The Moral Measure of the Economy (Maryknoll: Orbis Books, 2007), 6 & 59.
[2] “Credit Card Debt ‘Could be Halved by Interest Rate Cap’,” WHICH4U.co.uk, October 20, 2010.
[3] Lynn Parramore, “Exclusive Interview: Elizabeth Warren Says Big Banks Must Stop Blocking Reform,” Huffingtonpost.com, July 12, 2010.
[4] Bruce Watson, “Disturbing Statistics on the Decline of America’s Middle Class,” DailyFinance.com, October 17, 2010.
[5] See in general, Robert H. Frank, “Income Inequality: Too Big to Ignore,” NYTimes.com, October 16, 2010.
[6] Parramore, “Exclusive Interview: Elizabeth Warren Says Big Banks Must Stop Blocking Reform.”
Previous Post
June 5, 2011
Sophia, Science, and Homosexuality
Next Post
June 15, 2011 Beyond the Red Menace
Browse Our Archives
Select a Category Sophiology Uncategorized
Select a Month May 2017 March 2017 February 2017 December 2016 October 2016 December 2015 November 2015 October 2015 September 2015 August 2015 February 2015 January 2015 December 2014 November 2014 August 2014 July 2014 June 2014 May 2014 April 2014 March 2014 February 2014 January 2014 October 2013 September 2013 July 2013 May 2013 February 2013 September 2012 August 2012 June 2012 May 2012 April 2012 March 2012 February 2012 January 2012 December 2011 November 2011 October 2011 September 2011 August 2011 July 2011 June 2011 May 2011 October 2010
TAKE THE
Religious Wisdom Quiz
True or False: Moses entered the Promised Land before he died.
Select your answer to see how you score.
FALSE TRUE
Related posts from Faith With Wisdom
Religious liberty threatened, Trump promotes pop-religion
During Lent sacrifice ‘time’ not chocolate: take action
Atheists better than hypocritical Catholics says pope
Sophia’s intervention, how a nun’s simple gesture changed...
TRENDING AT PATHEOS Progressive Christian
Prayer for the Earth, to the Earth
What if we asked the Earth to pray for us? This lyrical...
An Insightful Look at Age-Gap Relationships in Scripture
If you've paid any attention to social media over the past 20...
Was God Silent for 400 Years, or Just...
God’s Global Footprints Across the Ages: How the Creator Has Always Been on...
Brandy Anderson, Team Weird, and Transcending Church
I met author Brandy Anderson on Heretic Happy Hour, when podcaster Keith...
Why Christians Have a Sacred Duty to Vote:...
The Bible offers strong support for the sacred duty to vote. Here...
What Being a Modern-Day Apostle Means to Me
In my last column, I discussed the ins and outs of modern-day...
view all Progressive Christian blogs
Ad-Free & Subscriber Log-In Subscription Support
- About Us
- 2026 Calendar
- Videos
- Podcasts
- Library of World Religions
- Faith In Media Tracker
- Advertise With Us
- Write for Us
- Privacy Policy
- Terms of Service
- Do Not Sell My Data
- Contact Us
- Radiant Digital
- Manage Newsletter Subscriptions
- Unsubscribe From Notifications
- Sitemap
Copyright 2008-2026, Patheos. All rights reserved.
Subscription Support Ad-Free & Subscriber Log-In
Follow Patheos